Pre-foreclosure in Mecklenburg County, North Carolina: what investors should know
A county with a young population, less free-and-clear equity than the U.S. average and a slowing building pipeline. Here is what that means for pre-foreclosure, probate and divorce deals around Charlotte.
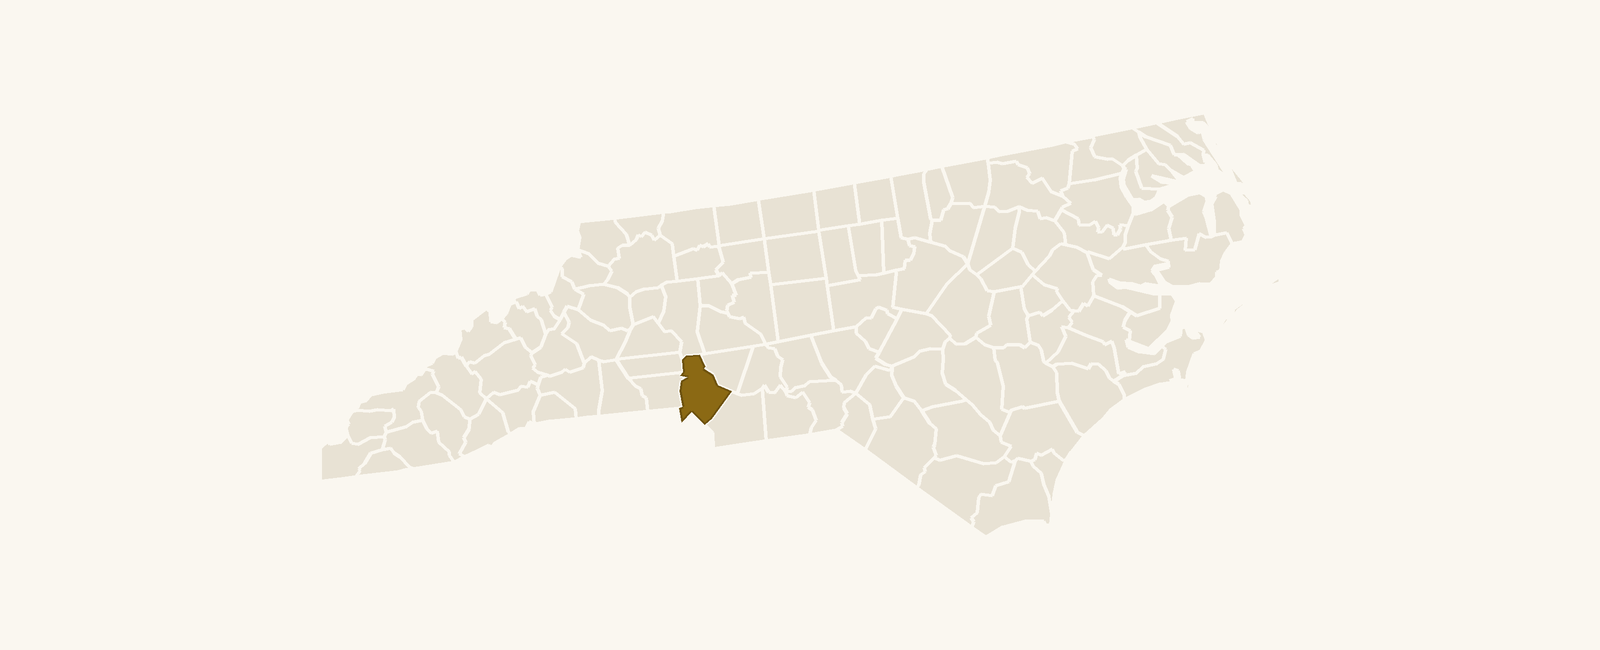
What Mecklenburg County's housing looks like
Mecklenburg County has 1,130,906 residents and 491,721 housing units, with Charlotte as the county seat. About 56% of homes are owner-occupied, and the median home value is $371K. That is a market with real money in the walls, which is why a distressed owner here often has options other than a quick sale to you.
Less free-and-clear equity than average. Only 25% of owner-occupied homes have no mortgage, compared with 39% across the U.S. Most owners here still carry a loan. That makes pre-foreclosure more relevant, but it also means you cannot assume a big equity cushion. Every deal needs its own payoff math.
A younger county. The median age is 35.4 against 38.9 nationally, and 12% of residents are 65 or older versus 17% nationally. Probate and estate sales exist here, but they will be a smaller share of the story than in an older county. Life events tied to jobs, family changes and mortgages carry more weight.
Newer, mixed housing stock. Just 2% of homes were built before 1940 (the U.S. figure is 12%), and 56% are single-family detached (61% nationally). Expect fewer century-old money pits and more townhomes, condos and newer subdivisions. Vacancy is 7% against 10% nationally, which points to a tighter market.
Source: U.S. Census ACS 2023
Which court filings come before a sale in Mecklenburg County
A filing is a signal that an owner may need to sell on a timeline. Each type tells you something different about the person on the other end.
- Pre-foreclosure: A lender has started the process after missed payments. The owner may still have equity and time, but is usually under stress.
- Probate: An owner has died and the estate is being opened. Heirs often live elsewhere and may not want to manage a house.
- Divorce: A couple needs to split an asset, and one or both may want a clean, quick sale.
- Tax sale: Unpaid property taxes have led to a tax foreclosure.
- Partition: Co-owners disagree about what to do with a shared property and ask a court to resolve it.
Real estate taxes in Mecklenburg County are due Sept. 1, and interest begins in January: 2% initially, then 0.75% per additional month. The county rate is 49.27 cents per $100 of assessed value, plus municipal taxes. The last general revaluation was in 2023. An owner who is behind on the mortgage is often behind on taxes too, so the two problems can stack.
How pre-foreclosure works in North Carolina, in plain terms
North Carolina homes are typically financed with a deed of trust, and foreclosure usually proceeds under a power of sale. That means the lender does not file a traditional lawsuit. Instead, the matter goes before the clerk of superior court, who holds a hearing, and a sale follows if the clerk allows it. After a sale, a period for upset bids generally applies before the sale becomes final. The statutes are in Chapter 45 of the North Carolina General Statutes.
Why this matters to you. The owner often has a window between the first filing and the sale, but it is not unlimited. Exact notice periods and deadlines depend on the case, so confirm timing with a North Carolina real estate attorney before you commit to anything.
Tax foreclosures are a separate track. Mecklenburg County handles in rem tax foreclosures in house through the County Attorney's office, while outside law firms handle other tax foreclosure listings. Sales are scheduled case by case, with notices published in the Mecklenburg Times for two weeks and posted at the courthouse for at least 20 days.
Tax foreclosure sales are held at the Mecklenburg County Courthouse in Charlotte and conducted by the Sheriff's office. Bidders must attend in person, since online bidding is not offered. The final bid then stays open 10 days for upset bids, and each upset must be at least 5% above the current high bid or a set minimum, whichever is greater. Winners pay the full bid by cash or certified or cashier's check, and receive a Sheriff's Deed after the Clerk confirms the sale.
Probate is handled through the clerk of superior court as well. If you want to see these records, they are public. Keystone delivers them matched to the owner and property and ready to work.
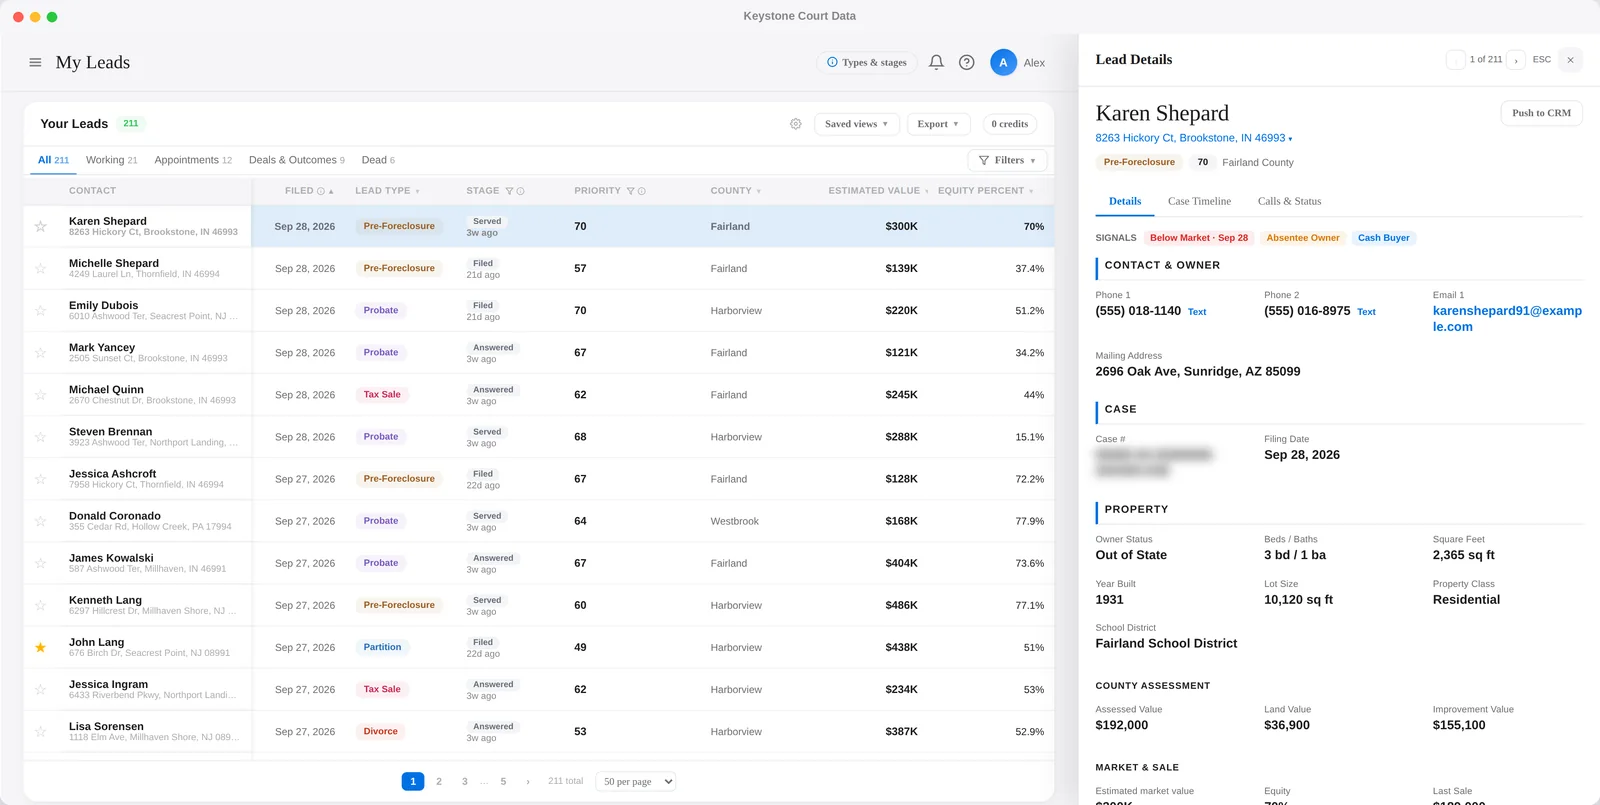
Pre-foreclosure leads in Mecklenburg County and the local economy
Charlotte is described by the county's economic development office as the second-largest banking center in the U.S. That has two effects worth thinking about. Many owners work in finance or related jobs, and a job change or relocation can quickly put a mortgage under strain. Lenders and servicers are also close to home, so a foreclosure here is rarely a surprise to the industry.
The county includes Charlotte, Cornelius, Davidson, Pineville, Huntersville, Matthews, Mint Hill and Stallings. Each has its own feel and buyer pool. A home in a suburban town may sell very differently than a condo in Charlotte, so price each deal against its own area, not the county median.
Permits are down. New housing units permitted in 2025 totaled 7,496, a 37% drop from 2024. Less new supply can support resale values and rents for the homes you buy, but it also tells you builders are cautious. Check that your exit still works if conditions shift.
Rents and what they mean for buy-and-hold
HUD Fair Market Rent for the Charlotte-Concord-Gastonia area is $1,686 monthly for a two-bedroom and $2,076 for a three-bedroom. These are benchmarks, not a promise of what a specific house will rent for. Still, they give you a starting point for testing a pre-foreclosure purchase as a rental.
With a median home value of $371K, rent-to-price ratios will be tighter than in cheaper markets. Many Mecklenburg deals will pencil out better as a flip or a wholesale assignment than as a hold, unless you buy well below market. Run the numbers on taxes, insurance and repairs before assuming the rent covers the cost.
How to approach owners respectfully and legally
People facing foreclosure, a death in the family or a divorce are often scared, embarrassed or grieving. Your first contact should be honest and low pressure. Say who you are, why you are reaching out, and that they are free to say no.
Follow the calling rules. If you phone, scrub against the National Do Not Call Registry and honor your own internal do-not-call requests. North Carolina also has telemarketing rules that may apply to you, so check them with an attorney. A letter or a visit that is polite and brief is often better received than a cold call.
Do not pressure or mislead. Never imply you are from the lender or the court. Do not promise to stop a foreclosure unless you can. Some states regulate how foreclosure-related offers are made, so have a North Carolina attorney review your contracts and your script.
Give people room. A family that just lost a parent may need weeks, not days. A divorcing couple may need both parties to agree. If an owner wants to talk to an attorney, a housing counselor or a family member first, encourage that.
What to look for before making an offer
- Total debt, not just the first mortgage. Second loans, unpaid property taxes and judgments can eat into the equity you think is there.
- Where the case stands. Ask an attorney how far along it is and what time remains, since the answer shapes how fast you must move.
- Who has authority to sign. In a probate or divorce situation, confirm who can legally sell. An attorney should verify this.
- Condition. With only 2% of homes built before 1940, many Mecklenburg properties are newer, but deferred maintenance in a distressed home still adds up. Walk it before you price it.
- Your exit. Test both a resale price and a rent against the area, using HUD benchmarks as one reference.
When you want filings delivered with the owner and property already matched, Keystone's Mecklenburg County page shows what is available, and you can try a county free for 7 days with no credit card.
Questions investors ask
Is North Carolina a judicial or non-judicial foreclosure state?
Most North Carolina mortgage foreclosures proceed under a power of sale in a deed of trust, with a hearing before the clerk of superior court. It is not a traditional lawsuit in the way many judicial states handle it. Confirm the exact steps and deadlines for a specific case with an attorney.
Can I still buy a home after a foreclosure sale in Mecklenburg County?
Often yes, but sales typically stay open for upset bids before they are final. For tax foreclosure sales here, the final bid stays open 10 days, and each upset must be at least 5% above the current high bid or a set minimum, whichever is greater. Winning bidders pay in full and receive a Sheriff's Deed after the Clerk confirms the sale.
Can I bid online at Mecklenburg tax foreclosure auctions?
No. Bidders must attend in person at the Mecklenburg County Courthouse in Charlotte, where the Sheriff's office conducts the sale. Payment must be cash or certified or cashier's check for the full bid.
Does a Mecklenburg County pre-foreclosure always mean the owner has equity?
No. Only 25% of owner-occupied homes here are owned free and clear, so most owners carry a loan, and some may owe close to what the home is worth. Always total up every lien and tax balance before you make an offer.
Can I call homeowners in foreclosure?
You can in many cases, but you must follow the National Do Not Call Registry and North Carolina telemarketing rules. Keep the call short, honest and respectful, and stop if the owner asks you to. Ask an attorney to review your outreach before you start.
See Mecklenburg County leads for 7 days, free
Real court filings with the owner and property matched. No credit card.