How to Make a Fair Offer on an Inherited House
Inherited homes come with grief, paperwork and several decision makers. Here is how to figure out who can sell, what the house is worth, and how to make an offer the family can respect.
- 1Confirm who has authority to sell
- 2Understand how many people have a say
- 3Value the house by condition and comparable sales
- 4Decide your margin and your ceiling
- 5Reach out gently and in writing first
- 6Present the offer and leave room to decide
Why a fair offer matters on an inherited house
A woman in her fifties opens a letter about her late father's house. She lives three states away, has never managed a rental, and has two siblings who disagree about what to do. If you are the one writing to her, your offer is more than a number. It is a first impression during one of the hardest months of her year.
If you are wondering how to make an offer on an inherited house, start by understanding that heirs rarely sell because they are careless. They sell because the house is a burden: taxes, insurance, utilities, repairs, a drive across the country, and a family that has to agree. A solution that removes that burden at a fair price is genuinely useful to them.
Fair is also good business. Heirs talk to attorneys, real estate agents, siblings and friends. An offer that is explainable, with reasons tied to the house's condition and the market, survives those conversations. A lowball with no explanation usually does not.
Inherited property also has legal wrinkles that ordinary sales do not. Title may not have passed yet, a court may need to approve certain sales, and several heirs may each hold a share. Making an offer without understanding those pieces wastes time for everyone.
The steps
- 01
Confirm who has authority to sell
Ask who is serving as executor or administrator, and whether the court has formally appointed them. Court records on probate cases are public. Without that authority, a family member cannot usually deliver clean title, so do not negotiate price with someone who cannot sign.
- 02
Understand how many people have a say
A will may leave the house to several people, or no will may exist and state law decides who inherits. Every person with an ownership interest, or the personal representative acting for them, may matter at closing. Ask politely who else is involved so you are not surprised later.
- 03
Value the house by condition and comparable sales
Walk the property if you are invited, and note the roof, systems, foundation, and any belongings that must be cleared. Compare recent sales of similar nearby homes, then subtract realistic repair, holding, closing and resale costs. Write down your math so you can explain it plainly.
- 04
Decide your margin and your ceiling
Settle on the smallest profit that makes the deal worth your time and the highest price you can pay. A number you can defend feels fair to a seller. Remember that a heir who gets a clear explanation is more likely to say yes than one who gets a bare figure.
- 05
Reach out gently and in writing first
A short, kind letter that offers a conversation, not a countdown, is a good first contact. If you do phone, check the Do Not Call Registry and your state's telemarketing rules first, call at reasonable hours, and stop when asked. Never imply you are connected to the court.
- 06
Present the offer and leave room to decide
Share your price, your timeline, who pays closing costs, and what condition you will take the house in. Encourage the family to talk with an estate attorney or their own agent. Then give them space, because a seller who feels respected is the one who comes back.
Common mistakes when offering on an inherited property
Most failed inherited-house deals fail for the same handful of reasons. All of them are avoidable.
- Negotiating with a relative who has no legal authority to sell.
- Ignoring other heirs, then discovering one of them refuses to sign.
- Offering based on the house as you imagine it, not as it actually is inside.
- Using a countdown or "this offer expires tonight" pressure on grieving people.
- Promising a closing timeline before you know whether the court is involved.
- Giving the impression you are an attorney or a court official.
Do not give legal or tax advice. Heirs will ask whether they will owe tax on a sale, or whether they need a lawyer. The honest answer is that it depends on their situation and state, and that they should ask an estate attorney or tax professional. Pointing them there builds trust.
Do not rush the timeline. Families sometimes need time to clear belongings, hold a memorial, or simply absorb the loss. An investor who says "take the time you need, here is my number when you are ready" often gets the call later, while a pushy one gets blocked.
Finally, watch how you phrase the contact itself. Calls and texts to people you do not know are covered by the Do Not Call rules and state telemarketing laws, so a respectful letter is usually the safer first step.
What to do after your offer is accepted
Acceptance is the start of the slow part. If the estate is in probate, the sale may need steps that a normal purchase does not, and your closing date should have room for them.
Put everything in a written contract that names the seller in their legal capacity, for example the executor of the estate, and not just by name. Ask the title company or closing attorney to confirm what documents the court and the title insurer will require. Some situations need a court order or confirmation before closing, and others do not. The rules vary by state, and sometimes by county.
Keep communication simple. Tell the seller what happens next, who they will hear from, and roughly what you need from them. Executors are often doing this for the first time, and a clear list of steps makes them far more comfortable.
Plan for delays without blaming anyone. A missing death certificate, a sibling who is slow to respond, or a court calendar can push a closing back. Build a flexible window into the contract and stay friendly. Heirs remember who stayed patient, and they refer friends who inherit homes later.
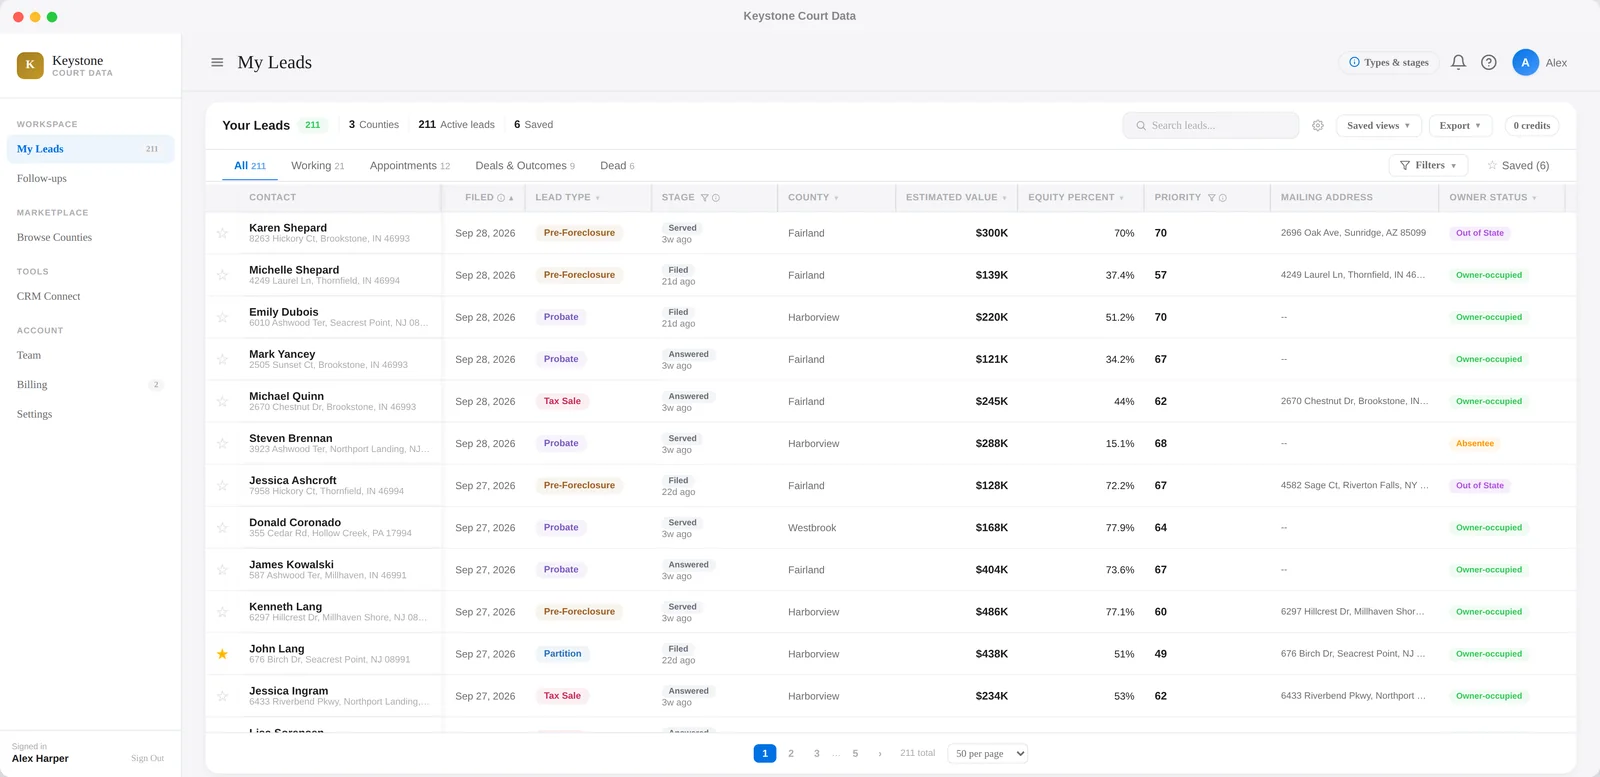
If you want leads where the filing and owner are already matched, Keystone's probate leads are built for that. Either way, the offer itself should stand on fairness and clarity.
Questions investors ask
Can I make an offer on an inherited house before probate is finished?
You can talk with the family, but the person signing must have legal authority to sell. Sometimes that authority comes from the court only after an executor or administrator is appointed. Ask the estate attorney or title company what is needed in that state.
Who do I make the offer to?
Usually the executor or administrator, since they act for the estate. If there is no court-appointed person yet, ask the family who is handling the matter and whether an attorney is involved. Do not assume the relative who answers the phone is the decision maker.
Should I offer less because the house is inherited?
Not because it is inherited. Your price should reflect condition, comparable sales, repair costs and your margin. Heirs sometimes accept a lower number for convenience, but they should understand your reasoning and be free to compare it.
Does the court have to approve the sale?
It depends on the state, whether there is a will, and how the will or local law gives the executor power to sell. Some sales proceed without court approval and others need it. Confirm with the county probate court or an estate attorney.
Can I call heirs to ask about the house?
You can, but you must follow federal Do Not Call rules and your state's telemarketing laws. Be brief, courteous and honest about who you are, and end the conversation if they ask you to. A letter is a gentler first step.
See leads in your county for 7 days, free
Real court filings with the owner and property matched. No credit card.