How to Estimate Equity on a Pre-Foreclosure Property, Step by Step
Equity decides whether a distressed owner can sell, whether a deal pencils, and how you should approach the conversation. Here is a careful way to build the estimate and know how much to trust it.
- 1Establish a realistic market value
- 2Adjust for condition
- 3Find the mortgage payoff, not just the balance
- 4Add every other claim on the property
- 5Subtract the cost of selling
- 6Calculate equity and stress-test it
Why estimating equity pre foreclosure shapes everything else
A homeowner who has missed payments for several months can look identical on paper to one who is sitting on a large cushion. The difference only shows up when you do the math. How to estimate equity pre foreclosure is therefore the first real question, ahead of price, ahead of strategy, and ahead of whether to reach out at all.
Equity tells you what kind of conversation to have. An owner with meaningful equity usually has choices: sell on the open market, negotiate with the lender, or work out a sale that pays everyone and leaves cash behind. An owner with little or none may need a short sale, a cash offer that closes quickly, or advice from a housing counselor or attorney.
It also keeps you honest. If you guess high, you waste the owner's time and yours. If you guess low and present it as fact, you may take advantage of someone who is already under stress, and that can create real legal and reputational trouble.
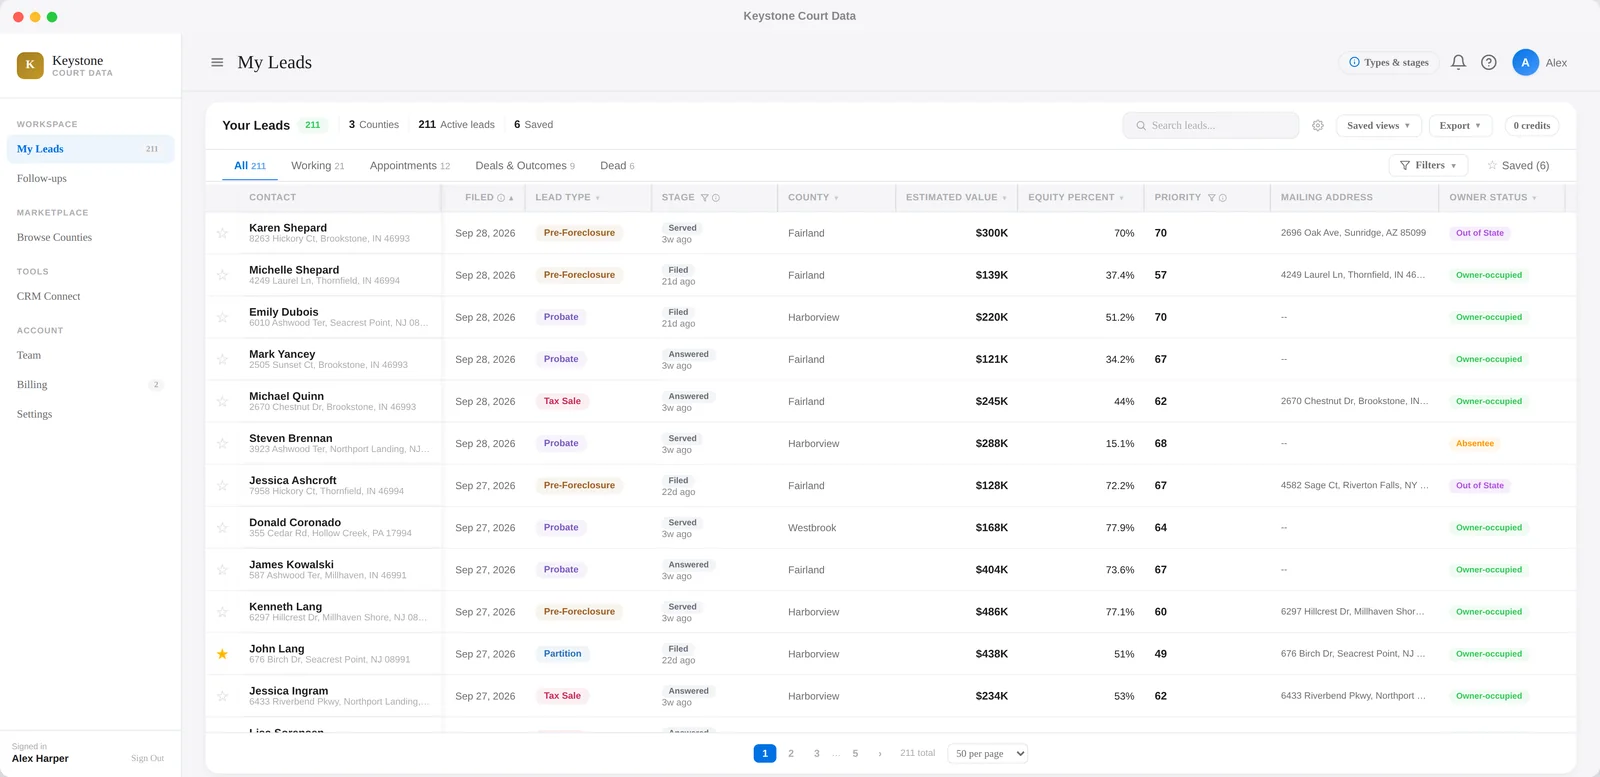
Pre-foreclosure filings are public records, and the rules for how the process unfolds differ by state and sometimes by county. Keystone Court Data delivers pre-foreclosure leads with the owner and property already matched, so you can spend your time on the analysis in this article instead of on paperwork.
The steps
- 01
Establish a realistic market value
Start with recent sales of similar homes nearby, adjusted for size, age, condition and features. A local agent's broker price opinion or a licensed appraiser gives you a sturdier figure than an automated estimate alone. Write your value as a low, middle and high number rather than a single guess.
- 02
Adjust for condition
Value the home as it actually sits today, not as a renovated comparable. If you cannot see inside, assume deferred maintenance and keep your low figure closer to the middle. An owner walkthrough or exterior photos can narrow the range considerably.
- 03
Find the mortgage payoff, not just the balance
The court filing typically states what the lender is claiming, which gives you a starting point. The true payoff adds accrued interest, late charges, fees and any advances the lender made. Only a payoff statement from the servicer, which the owner can request, gives the exact figure.
- 04
Add every other claim on the property
List second mortgages, home equity lines, tax liens, judgments, mechanic's liens, unpaid association dues and any past-due property taxes. Priority differs by lien type and state, but all of them usually have to be cleared or resolved at closing. Ask the owner what they know, and have a title company confirm.
- 05
Subtract the cost of selling
Include agent commissions if the home will be listed, closing costs, transfer taxes, expected repairs and the carrying costs of holding the property until closing. Use conservative allowances in each category. Costs vary by market, so ask a local agent or title company what is typical.
- 06
Calculate equity and stress-test it
Subtract the total claims and selling costs from your low, middle and high values. If equity stays positive even at the low value, the owner likely has room to work with. If it turns negative at the middle value, plan for a lender-approved sale or a different conversation.
Common mistakes that wreck an equity estimate
Using the original loan amount or an old statement. A missed-payment loan keeps growing. Late fees, interest, property inspection charges, legal costs and sometimes advances for taxes or insurance get added to the payoff. The number you see on a year-old statement is a floor, not the payoff.
Trusting an automated online value without context. Those estimates cannot see a failing roof, deferred maintenance, a bad addition or a smoke-damaged kitchen. Distressed owners often stop repairing things long before they stop paying, so condition tends to run worse than the averages suggest.
Forgetting everything behind the first mortgage. A second mortgage, a home equity line, an unpaid contractor lien, a tax lien, a judgment or unpaid homeowners association dues all sit in line for payment at closing. Any one of them can turn a good-looking spread into a loss.
Ignoring selling costs. Commissions, closing costs, transfer taxes, repairs the buyer will demand and carrying costs while the deal closes all come out of the owner's proceeds. Skipping them overstates equity every time.
Presenting the estimate as certain. You are working with incomplete information. Say so, and invite the owner to correct you.
What to do after you have a number
Match your approach to the equity. Healthy equity points toward a conversation about selling on the open market or a fair cash offer with real cushion for the owner. Thin equity points toward a short sale, a lender-approved deal or a referral. Negative equity means the owner likely cannot sell without lender approval, and you should be upfront about that.
Keep the first contact low-pressure. Introduce yourself, say plainly why you are reaching out, and offer to answer questions without asking for a decision. Many owners in this position are overwhelmed, embarrassed or already getting aggressive calls.
If you phone, check the National Do Not Call Registry and your state's telemarketing rules before you dial, honor internal opt-out requests, and respect calling-hour limits. A short, polite letter is often better received than a cold call, and it gives the owner time to think.
Encourage owners to talk with their servicer about loss mitigation options, a HUD-approved housing counselor and an attorney licensed in their state. Do not give legal advice yourself. If you are an agent or investor, document what you told the owner and when.
Questions investors ask
What is the simplest equity formula for a pre-foreclosure home?
Equity equals realistic market value minus the full mortgage payoff, minus all other liens and claims, minus costs of sale. The payoff is the key detail because it includes arrears, interest and fees on top of the principal. Run the formula at a low, middle and high value to see how sensitive the result is.
Can I trust the amount stated in the foreclosure filing?
Treat it as a useful starting point, not the final payoff. The filing generally reflects what the lender claimed at that moment, and costs keep accruing afterward. Ask the owner to request a written payoff statement from the servicer for the real number.
Does the owner owe me an explanation of what they owe?
No, and you should not push for financial details they are not comfortable sharing. Explain why the numbers help, offer to work from rough figures, and let them decide. Respect a no, and never pressure someone who is already stressed.
What if the estimate shows no equity?
Then a standard sale may not cover what is owed, and the lender would have to approve a short sale. Be direct about that, avoid promising outcomes, and point the owner toward a housing counselor or an attorney. Some owners will still want to explore options, and an honest answer builds trust.
Do the rules about equity and surplus differ by state?
Yes. Foreclosure procedures, timelines, how surplus is handled after a sale and what rights an owner has to stop or reverse the process vary by state. Confirm the specifics with the county court or a licensed attorney before you advise or act.
See leads in your county for 7 days, free
Real court filings with the owner and property matched. No credit card.