Pre-foreclosure in Erie County, New York: what investors should know
Older homes, a lot of owners with no mortgage, and a state where foreclosure runs through the courts. Here is how that shapes deals in Erie County.
What the Erie County housing market looks like
Erie County has 950,044 residents and 439,987 housing units, and 65% of homes are owner-occupied. If you are researching pre-foreclosure Erie County New York, that owner-occupied base is where most of your conversations will happen. The county seat is Buffalo, the second largest city in the state, and the county has three cities and 25 town governments.
The median home value is $217K. Vacancy is 7%, below the U.S. figure of 10%, which suggests homes here do not sit empty as often as in many markets. Single-family detached homes make up 59% of the stock, close to the national 61%.
Rents matter if you plan to hold. HUD Fair Market Rent in the Buffalo-Cheektowaga area is $1,423 a month for a 2-bedroom and $1,732 for a 3-bedroom. New housing permits in 2025 came to 1,213 units, unchanged from 2024 (+0%), so new construction is not rapidly adding competing supply.
Major employers include State and Federal government, Kaleida Health, SUNY Buffalo, Catholic Health Systems, Employer Services Corporation, Tops Markets LLC and M & T Bank. Stable institutional employers tend to support steady rental demand.
Source: U.S. Census ACS 2023
Old houses and free-and-clear owners: what sets Erie County apart
Two numbers stand out. Homes built before 1940 are 30% of the stock here, compared with 12% across the U.S. And 42% of owner-occupied homes have no mortgage, compared with 39% nationally.
Old housing means a repair budget comes first. A pre-1940 house may have outdated wiring, plumbing, roofing or heating, and it may have deferred maintenance if the owner was under financial stress. Walk every property before you commit, and bring a contractor if you are not one yourself.
Free and clear means more equity in the room. When an owner has no mortgage, a probate, divorce or tax-lien situation is less about escaping debt and more about a family sorting out value. That changes your conversation. Sellers in that position often have options, so a fair offer and clear communication matter more than speed.
The population is also older than average. Residents aged 65 or older are 19% of the county (U.S.: 17%), and the median age is 40.3 (U.S.: 38.9). That points to estate and downsizing situations being a steady part of the picture here.
Which court filings come before a sale in Erie County
A court filing is a signal that a property may change hands. Each type means something different about the owner's situation.
- Pre-foreclosure: A lender has filed a court case over missed mortgage payments. The owner still holds title and may want to sell, catch up, or negotiate.
- Probate: An owner has died and the estate is going through court. Heirs or an executor may want to sell a house they do not want to keep, especially an older one that needs work.
- Divorce: A couple may need to sell or buy out a spouse. Sensitivity and patience matter most here.
- Tax sale: Unpaid property taxes have led to a county tax foreclosure.
- Partition: Co-owners disagree and the dispute ends up in court. This often happens with inherited property.
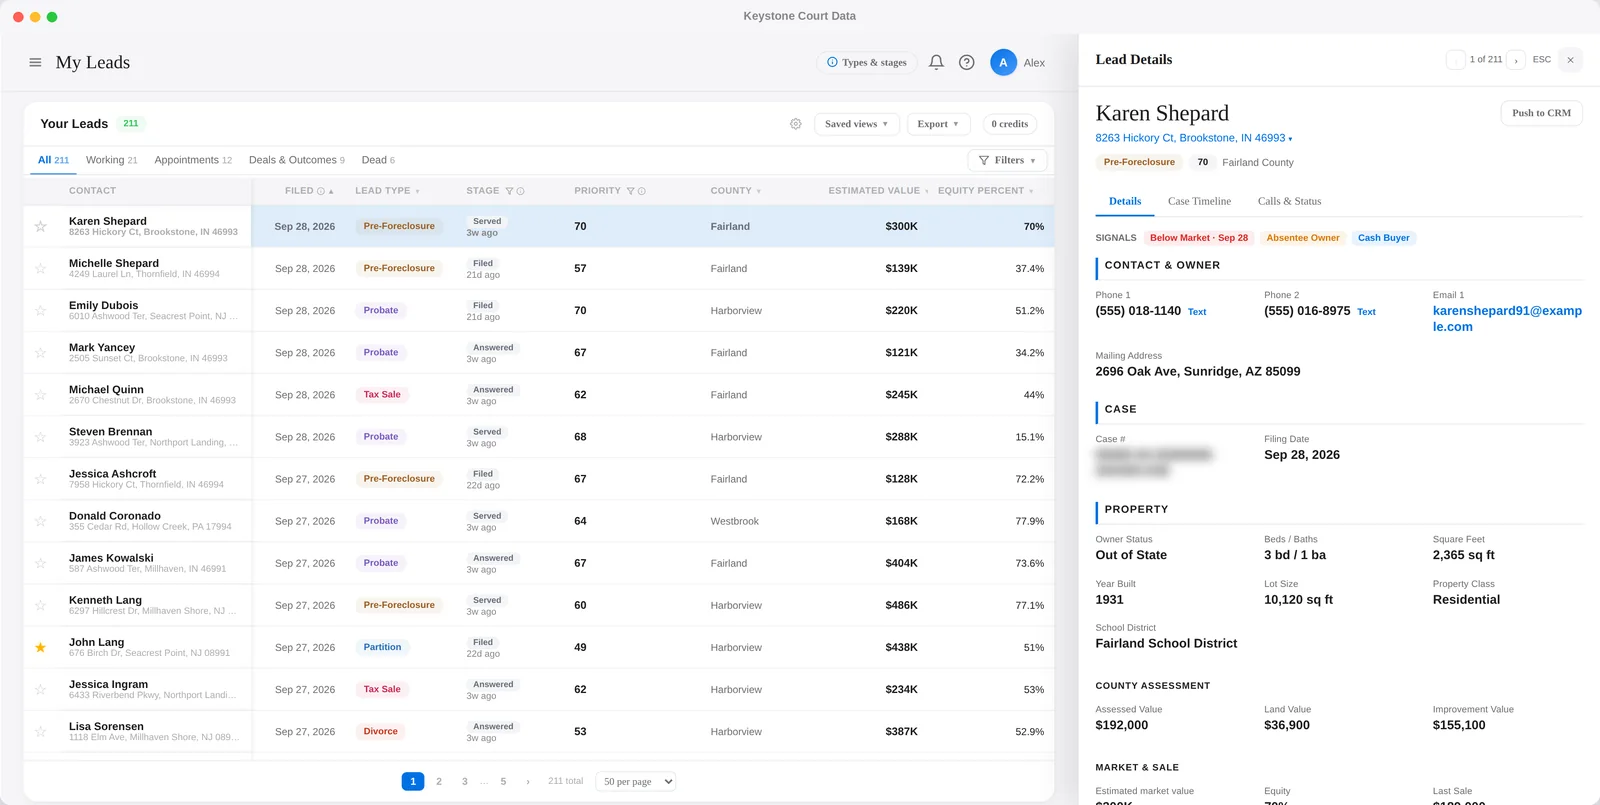
These are all public court records. If you want them delivered with the owner and property already matched, Keystone's Erie County page covers pre-foreclosure, divorce, probate, tax sale and partition filings.
How foreclosure works in New York, in plain terms
New York is a judicial foreclosure state. A lender has to file a lawsuit and get a court order before a home can be sold. Before filing on a home loan, the lender has to send the borrower a 90-day pre-foreclosure notice, covered in RPAPL section 1304. Residential foreclosures also include a mandatory settlement conference. Timelines and requirements vary by case. These lawsuits are brought in the New York State Supreme Court; the official New York State Unified Court System website (nycourts.gov) carries the courts' own information.
Sheriff's sale terms are strict. Erie County Sheriff's sales of real property are held under a writ of execution issued out of Supreme Court. According to the Sheriff's published sale notices, bidders pay by cash or attorney or bank check, with at least 10% down. The balance is due by 4:00 PM the next business day. If you miss the balance deadline, the down payment may be forfeited, and the Sheriff may accept or reject any bid.
Tax foreclosure runs on a local law. The Erie County Tax Act is a state law that applies only to Erie County. The county can foreclose on tax liens unpaid for two or more years, and each round has a last day of redemption. For In Rem 174, that date was July 6, 2026. Foreclosed properties are ultimately sold at an annual auction, with the Director of Real Property Tax Services acting as Referee and notice published once a week for three weeks.
Auction buyers pay a 20% deposit in certified funds or cash, with the balance due within 30 days at closing. The county does not take title. You receive a Referee's Deed and buy the property as-is.
Tax calendars help explain when owners fall behind. In the Town of Clarence, for example, Town and County bills go out by mid-January and are due around February 15, and school bills go out by mid-September and are due around October 15. Penalties escalate after the due date. Other towns have their own schedules.
Probate goes through the Surrogate's Court. In New York, estates are handled by the Surrogate's Court. The court issues letters to the person who handles the estate (the fiduciary), so ask to see those letters and let the estate's attorney guide timing.
How to approach owners respectfully and legally
The people behind these filings are often dealing with a death, a divorce or money trouble. Lead with honesty. Say who you are, what you do, and that there is no pressure to respond.
Mail or knock gently before you call. A short, plain letter is easy to ignore or answer on the owner's own schedule. If you do phone, follow the National Do Not Call Registry and the federal telemarketing rules, and keep your own internal do-not-contact list. Stop contacting anyone who asks you to.
Be careful with foreclosure purchases. If you buy from an owner in foreclosure, a real estate attorney can confirm that your paperwork complies.
Never imply you are with the court, the lender or the county. Never promise to stop a foreclosure unless you can. Encourage owners to speak with their own attorney or a HUD-approved housing counselor. A seller who feels respected is far more likely to deal with you, and to recommend you to others.
What to check before you make an offer
Confirm the stage of the case. A foreclosure that has just started gives the owner time and options. One heading toward a court-ordered sale is tighter. Ask the owner or their attorney where things stand, and have your own attorney confirm legal deadlines.
Price in the age of the house. With so many pre-1940 homes, budget for systems, not just cosmetics. Inspect for roof, foundation, wiring, plumbing and heating issues, and consider lead paint and other hazards common in older housing.
Understand title and liens. A title company or attorney should confirm what you would actually own and what would remain attached. At a county tax auction you get a Referee's Deed and the property comes as-is, so do your homework before you bid.
Run the numbers both ways. For a flip, compare your all-in cost to the $217K median home value as a rough reference, then to real comparable sales. For a rental, check your math against the HUD rent figures of $1,423 for a 2-bedroom and $1,732 for a 3-bedroom, then adjust for the specific neighborhood and condition.
Have your funds ready. Sheriff's sales and tax auctions both set short payment windows, and failing to close can cost you your deposit. Line up cash or certified funds before you commit.
Questions investors ask
Is New York a judicial or non-judicial foreclosure state?
New York is a judicial foreclosure state. A lender must file a lawsuit and obtain a court order before a home can be sold, and timelines vary by case.
How do I pay at an Erie County sheriff's sale?
According to published sheriff's sale notices, payment is by cash or attorney or bank check. At least 10% is due down, and the balance is due by 4:00 PM the next business day. The down payment may be forfeited if you miss the deadline, and the Sheriff may accept or reject any bid.
How is Erie County tax foreclosure different?
It follows the Erie County Tax Act, a state law that applies only to Erie County. The county can foreclose on liens unpaid for two or more years, and properties are ultimately sold at an annual auction. Buyers pay a 20% deposit, have 30 days to close, and receive a Referee's Deed on an as-is basis.
Can an executor sell a house in Erie County?
It depends on the will and the estate. The executor or administrator acts under letters issued by the Surrogate's Court, so ask to see them and let the estate's attorney set the timing. Rules vary by estate, so confirm details with an attorney.
Can I call homeowners in foreclosure?
You can in many cases, but you must follow the National Do Not Call Registry rules. Many investors prefer a short, respectful letter first. Stop contacting anyone who asks you to, and have an attorney review your approach.
See Erie County leads for 7 days, free
Real court filings with the owner and property matched. No credit card.