Pre-foreclosure in Dallas County, Texas: what investors should know
Texas forecloses outside of court, the county is younger and more renter-heavy than the U.S. as a whole, and many owners hold no mortgage. Here is what that means when you look for motivated sellers around Dallas.
What Dallas County's housing looks like
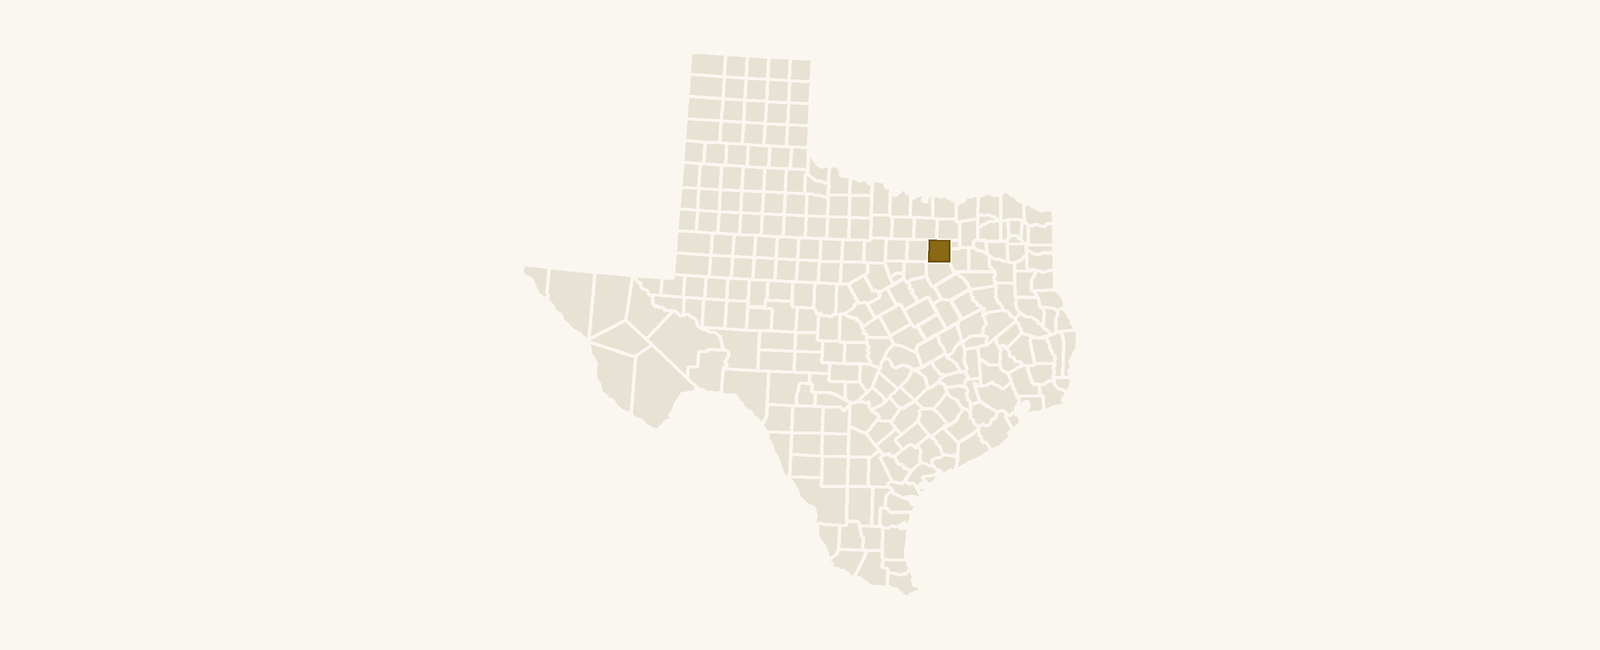
Dallas County has 1,053,471 housing units and 2,603,816 residents, and only 51% of homes are owner-occupied. That is a renter-heavy county, and it shapes everything about pre-foreclosure Dallas County Texas investors work with. The pool of owners who can fall behind on a mortgage is only part of the housing stock.
Newer owners, younger county. The median age of residents is 34.0, against 38.9 for the U.S. Only 12% of residents are 65 or older, compared with 17% nationally. In practice, you are more likely to meet a mortgaged owner in mid-career than a retiree who has owned for decades.
Plenty of equity, but not everywhere. The median home value is $278K, and 42% of owner-occupied homes are owned free and clear (U.S.: 39%). A home with no mortgage will not go through a mortgage foreclosure, but it can still show up through a death, a divorce, or unpaid taxes. Those owners often have the most room to negotiate.
Newer stock, fewer old-house surprises. Just 4% of homes were built before 1940 (U.S.: 12%), and 52% are single-family detached (U.S.: 61%). Expect fewer century-old homes with knob-and-tube wiring, and more townhomes, condos and apartment-style units in the mix. Vacancy is 8% against 10% for the U.S., which points to steady demand for housing.
Source: U.S. Census ACS 2023
Which filings come before a sale in Dallas County
A distressed sale rarely comes out of nowhere. Something happens to the owner first, and a public record usually marks it. Knowing what each record means tells you how motivated, and how pressed for time, the owner may be.
- Pre-foreclosure notices. A lender's notice of default and later notice of sale mean the owner is behind on a loan and a sale date is coming. The owner still holds title and can still sell, refinance, or catch up.
- Probate. When an owner dies, the estate goes through the probate court. A personal representative often needs to sell a home they never wanted to keep, especially if heirs live elsewhere.
- Divorce. Texas is a community property state, so a home bought during the marriage is generally part of what gets divided. Selling and splitting the proceeds is a common outcome.
- Tax sale and partition. Unpaid property taxes can lead to a tax suit and sale. Co-owners who cannot agree, such as siblings who inherited together, may ask a court to order a partition.
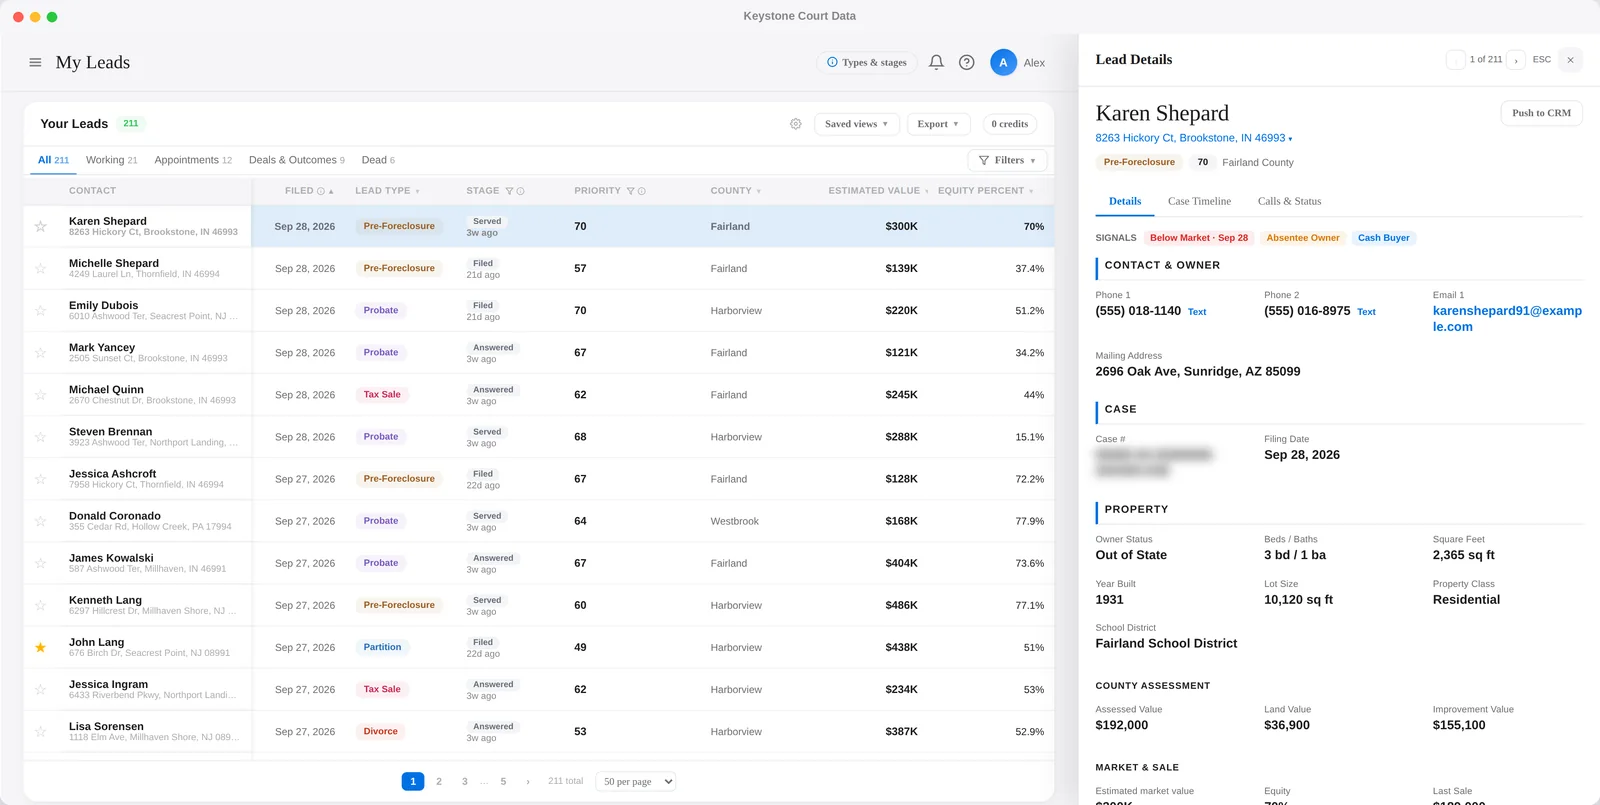
The records behind all of these are public at the county. If you want them matched to the owner and property and ready to use, Keystone's Dallas County page shows what that looks like.
How the pre-foreclosure process works in Texas
Texas is mainly a nonjudicial foreclosure state. Most home loans include a deed of trust with a power of sale, so the lender can foreclose without suing first. Some loans, such as home equity loans and reverse mortgages, require a court order before a sale, so the path depends on the loan type.
The notice of default. Texas law generally requires the lender to give the borrower written notice of default and at least 20 days to cure before it moves to the next step. Curing means catching up on what is owed.
The notice of sale. After that, a notice of sale has to be given at least 21 days before the sale date. It is sent to the borrower, filed with the county clerk, and posted publicly at the place the county designates.
The sale itself. Foreclosure sales are held on the first Tuesday of the month, within a set window of the day, at the location designated for the county. For Dallas County, check the county's official site and the Dallas County Clerk for the current details. Texas does not give mortgage borrowers a statutory right to redeem the home after the sale, so the owner's real options sit before that Tuesday.
That is why the weeks between the notices and the sale date matter so much. Rules differ by loan type and can change, so confirm specifics with the county clerk or a Texas real estate attorney before you rely on any timeline.
Approaching owners with respect and within the law
An owner facing foreclosure is usually stressed, embarrassed, and getting a lot of mail. A calm, honest approach stands out. Say who you are, what you do, and that you are not asking for a decision on the spot.
Be clear about what you are. You are a buyer, not a rescuer. Do not promise to save the home or imply you are connected to the lender. Do not pressure anyone, and do not hint that time is running out in ways that are not true.
Check phone rules first. Before you call, screen numbers against the National Do Not Call Registry and follow Texas telemarketing rules, including any registration or calling-hour requirements that apply to you. A letter is often a gentler first contact than a cold call.
Suggest they get advice. Encourage owners to talk to a HUD-approved housing counselor or an attorney. If a seller leaves with better options, you have lost nothing. Many will remember the honest buyer later.
Estate and divorce sellers need even more care. The person you reach may be grieving or in conflict, and they may not be the only decision-maker. Ask who has authority to sell, and be patient.
Rent numbers for buy-and-hold in Dallas County
With only half of homes owner-occupied, rental demand is a large part of the market here. HUD's Fair Market Rent for the Dallas-Fort Worth-Arlington area is $1,807 a month for a 2-bedroom and $2,275 for a 3-bedroom. Those are benchmark figures, not guarantees of what a specific property will rent for.
New supply also matters. The county had 12,691 new housing units permitted in 2025, and the change from 2024 was -0%, so building is holding steady rather than surging or collapsing. For a buyer of distressed homes, that means you compete with new construction for tenants and with other buyers for older stock.
Run your own numbers against current local rents, taxes, and insurance before you commit. A home bought below market value can still be a poor rental if the numbers do not hold up.
What to check before you make an offer
A pre-foreclosure deal is only as good as the title and the numbers behind it. Slow down on these points before you put money down.
- Liens and loan position. Find out what is owed and to whom. A second lien, a tax lien, or a home equity loan can change what a deal is worth, and a lien that survives a sale becomes your problem.
- Who can sign. For estates, confirm who has legal authority to sell. For divorces, confirm what the court has ordered and whether both spouses must agree.
- Condition. Newer stock helps, with few homes built before 1940, but a home that has sat during a dispute can still have deferred repairs. Walk it if you can, and budget for surprises.
- Timeline. Know the sale date and plan a closing that fits. If the sale is close, the owner may need a faster path than a standard closing allows.
- Professional help. Use a Texas title company and an attorney for contracts, especially when buying from owners in distress. Rules on these deals vary and are not something to guess at.
Questions investors ask
Is foreclosure in Dallas County judicial?
Usually no. Texas mostly uses nonjudicial foreclosure under a deed of trust with a power of sale, so the lender does not need to file a lawsuit first. Some loans, such as home equity loans and reverse mortgages, require a court order, so the loan type matters.
When do foreclosure sales happen in Dallas County?
Texas foreclosure sales take place on the first Tuesday of the month, during a set window of the day, at the location the county designates. The notice of sale gives the exact place and time.
Can an owner stop a foreclosure in Texas?
Yes, in several ways. An owner can catch up on what is owed, work out a modification or repayment plan with the lender, sell the home, or in some cases file for bankruptcy. A HUD-approved housing counselor or an attorney can explain which options fit a specific case.
Can I call homeowners in pre-foreclosure?
You can, but you must follow the National Do Not Call Registry and Texas telemarketing rules. Many investors start with a respectful letter instead. Be honest about who you are, and never pressure anyone.
Does 42% of owners being mortgage-free mean fewer deals?
It means fewer homes can go through a mortgage foreclosure, but it also means more equity when a home sells through probate, divorce, or partition. Those situations can be strong opportunities if you approach them with care and confirm who has authority to sell.
See Dallas County leads for 7 days, free
Real court filings with the owner and property matched. No credit card.