Investing in Maricopa County, Arizona: where motivated sellers show up in the court record
Equity, newer housing stock and a deed-of-trust foreclosure system shape how distressed sales happen here. This guide covers what the court filings mean and how to treat the people behind them.
What Maricopa County housing looks like for an investor
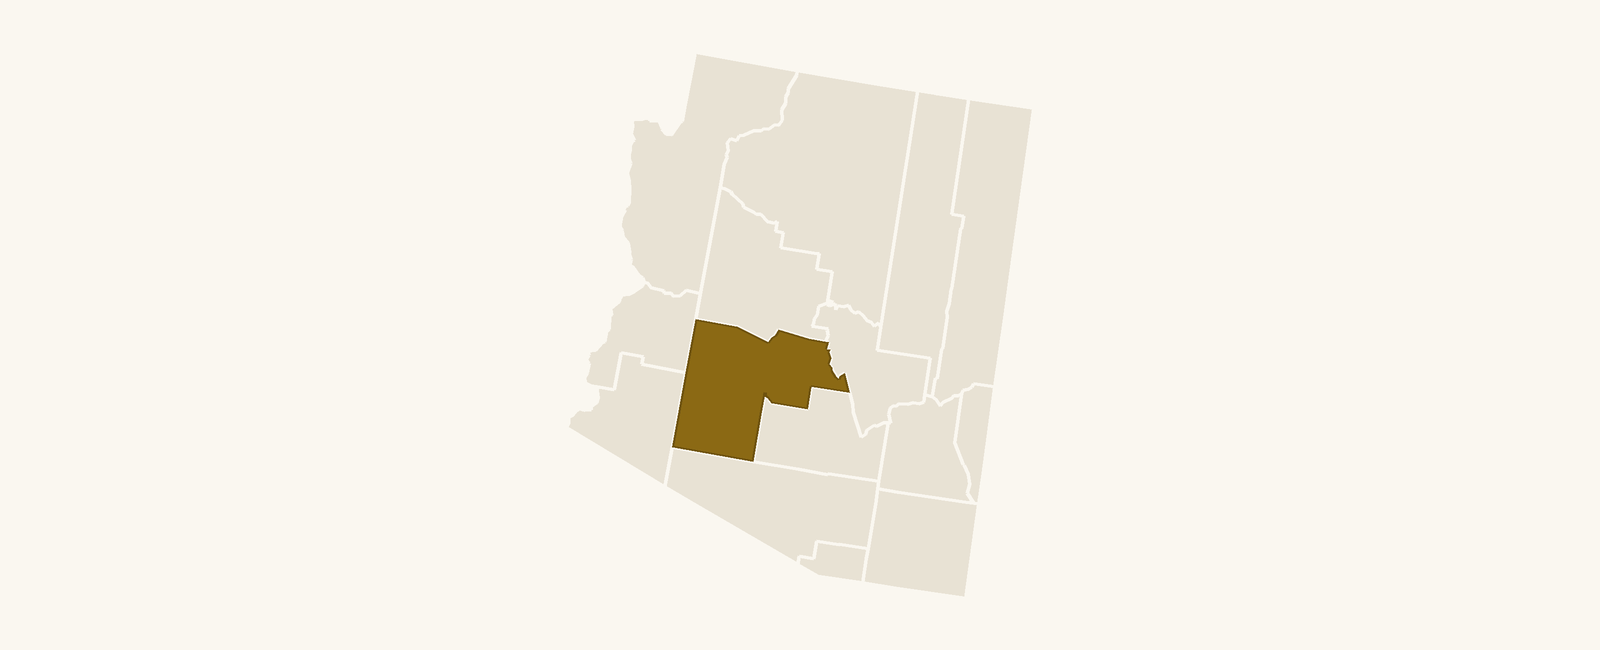
Maricopa County Arizona real estate investing starts with a very large, mostly suburban housing base. The county has 4,491,987 residents and 1,850,862 housing units, and Phoenix is the county seat. The median home value is $415K.
Single-family is the main product. About 64% of homes are single-family detached, compared with 61% for the U.S. Owner-occupied homes make up 65% of the stock, so a large share of what you will see is a family's primary residence, not a rental.
The housing is young. Just 1% of homes were built before 1940, against 12% nationally. That changes your repair budgeting. You are less likely to face knob-and-tube wiring or failing foundations from a century ago, and more likely to look at roofs, cooling systems, plumbing and finishes that have aged out or been neglected. Inspect for those on every property.
Equity is a little thinner than average. Owner-occupied homes with no mortgage are 33% here (U.S.: 39%). More owners carry a loan, which is part of why foreclosure filings matter to investors in this county. Vacancy is 8% (U.S.: 10%), which points to a tighter market than the national picture.
Source: U.S. Census ACS 2023
Rents and new construction: what they say about demand
For buy-and-hold math, HUD's Fair Market Rent for the Phoenix-Mesa-Chandler area is $1,734 per month for a 2-bedroom and $2,287 per month for a 3-bedroom. Those are benchmarks, not what any specific house will rent for, so confirm against actual local listings before you underwrite.
On the supply side, 31,651 new housing units were permitted in 2025, a change of -13% from 2024. Fewer permits can mean less new competition for resale buyers down the line, but it is one data point, not a forecast. Treat it as context for your hold-period assumptions.
Which court filings come before a sale here, and why
Court and recorded filings are public, and each one tells you something different about the owner's situation. Understanding the meaning matters more than the paperwork itself.
- Pre-foreclosure: The owner has fallen behind on a loan secured by a deed of trust. They may want to sell before a trustee's sale to protect what equity remains and their credit.
- Probate: An owner has died and the home is part of an estate. Heirs often live elsewhere and may prefer a clean, quick sale to managing a vacant house.
- Divorce: Arizona is a community property state, and a home acquired during the marriage is generally treated as shared. A court-ordered or agreed sale can follow.
- Tax-related filings: Unpaid property taxes can lead to a county lien sale process. Arizona handles this differently from states that sell the deed outright, so confirm the current procedure with the county treasurer or an attorney.
- Partition: Co-owners who cannot agree on what to do with a property may ask a court to order it sold.
Because 16% of residents are 65 or older (U.S.: 17%), age-related transitions are about as common here as nationally. Estate sales are a steady part of the market, not a dominant one.
How the process works in Arizona, in plain terms
Foreclosure is usually non-judicial. Most Arizona residential loans use a deed of trust, which lets a trustee sell the property without a lawsuit if the borrower defaults. The trustee records a notice of sale, and under A.R.S. 33-808 that notice must be recorded at least 90 days before the sale date. Arizona generally gives no right to redeem after a trustee's sale, so the window before the sale is where an owner has real options. Rules differ by loan type and situation, so confirm details with an attorney.
Probate runs through the Superior Court. In Maricopa County, estates are handled by the Superior Court, and a personal representative is appointed to manage the estate. That person, not the heirs as a group, typically has authority to sell estate real property, subject to the will and court requirements. Whether court approval is needed depends on the estate, so the representative should check with the court or an attorney.
Divorce is also a Superior Court matter. Property division follows community property rules, and a judge or the spouses' agreement decides who keeps or sells the home. Neither party may be free to sell on their own until that is settled.
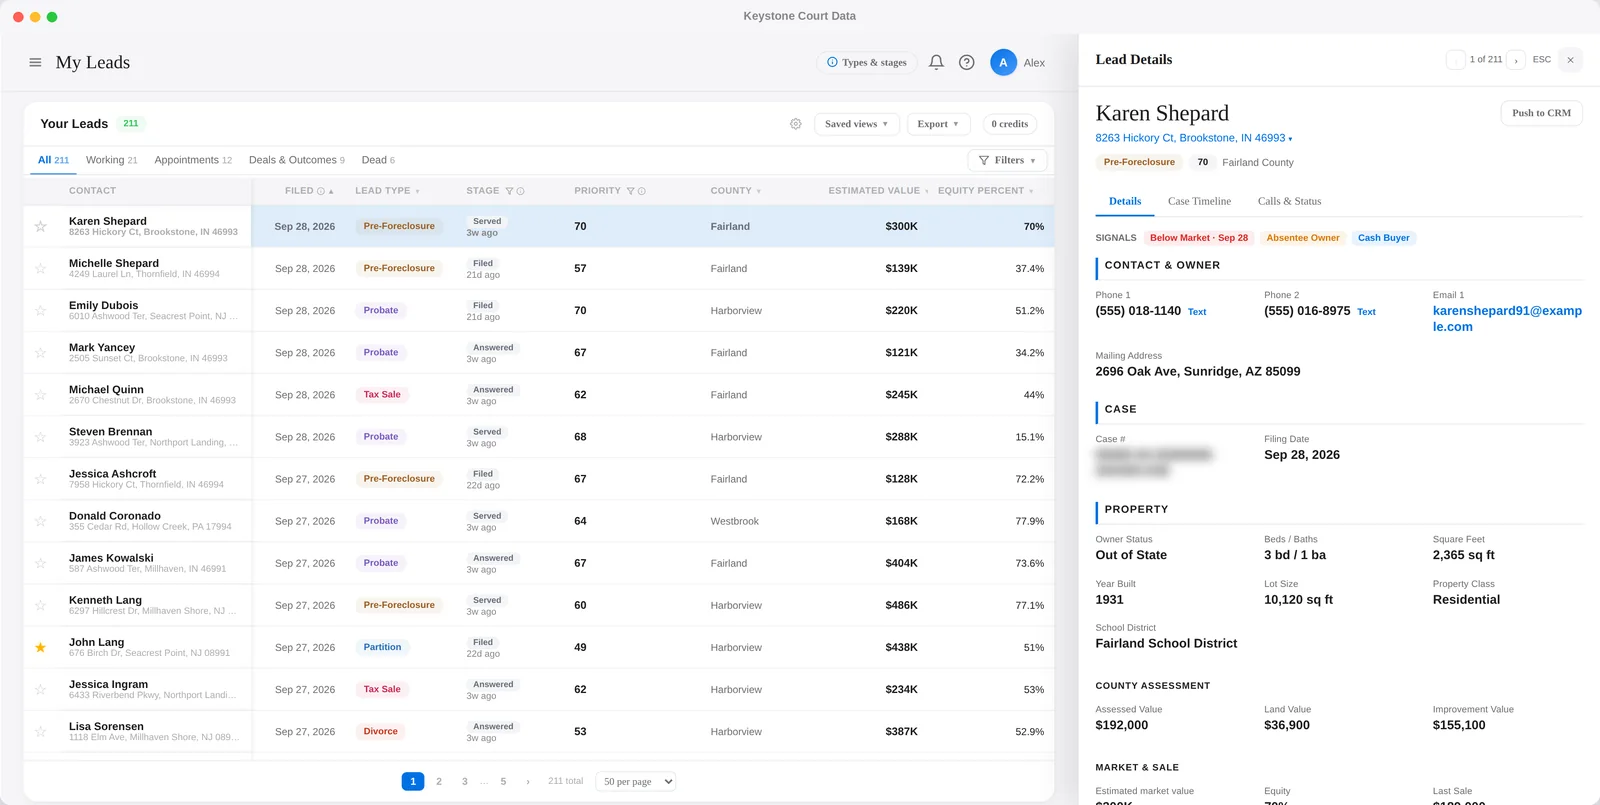
The records for all of these are public. If you want them delivered with the owner and property already matched, Keystone's Maricopa County page shows how that works.
How to approach owners respectfully and legally
Assume the person is under stress. A family dealing with a death, a divorce or missed payments is not looking for a sales pitch. Introduce yourself plainly, say why you are reaching out, and make it easy for them to say no.
Be honest about who you are and what you do. Say you are an investor, explain that you buy as-is, and never imply you are a lender, a court representative or a government agency. Do not suggest that a sale is the only way out. Encourage owners to talk to a housing counselor, attorney or their lender as well.
Mind the phone rules. If you call, check the National Do Not Call Registry and follow federal and Arizona telemarketing rules, including calling-hour limits and honoring opt-out requests. Rules for texts and prerecorded messages are stricter. Mail and in-person letters are often a gentler first contact, and an attorney can confirm what applies to your business.
Foreclosure rescue and equity-purchase rules can also apply when you buy from a distressed owner. Have a local attorney review your contracts and disclosures before you use them.
What to look for before making an offer
Start with title and liens. Confirm who actually has authority to sign: the owner, a personal representative, both spouses or all co-owners. In a foreclosure, learn the loan position and any junior liens, since a trustee's sale can leave some of them behind.
Next, inspect the condition. With few pre-1940 homes, plan around mid-life systems rather than ancient ones: roof, cooling, plumbing, water heater and any deferred exterior work. Heat and sun wear on materials differently than in other climates, so get a contractor's eyes on it.
Then run your numbers against both exits. For a flip, compare your projected resale to the $415K county median as a rough anchor, not as a comp. For a rental, check the HUD rents above against real listings, and account for vacancy, taxes, insurance and management.
Finally, give the seller room. Explain the offer in writing, allow time to review it with an advisor, and never rush someone through a signature. Fair, patient deals tend to close more reliably.
Questions investors ask
Is foreclosure judicial in Maricopa County?
Most residential foreclosures in Arizona are non-judicial, handled by a trustee under a deed of trust. Some situations, such as certain mortgages, can go through court instead. Ask an attorney which route applies to a specific loan.
Can an executor sell a house in Maricopa County?
A court-appointed personal representative generally has the authority to sell estate property, subject to the will and any court requirements. Heirs who are not the representative usually cannot sell on their own. The representative should confirm the steps with the Superior Court or an attorney.
Where can I see the court filings for this county?
They are public records. Keystone Court Data delivers pre-foreclosure, probate, divorce and other filings with the owner and property already matched, so you do not have to assemble them yourself.
Does the lower share of old homes mean fewer repairs?
Not necessarily. With only 1% of homes built before 1940, you will see fewer age-related structural surprises, but roofs, cooling systems and plumbing still wear out. Budget from an inspection of each property instead of assuming newer means move-in ready.
Can I call a homeowner who appears in a public filing?
You can, but you must follow the National Do Not Call Registry and federal and Arizona telemarketing rules. Keep calls brief, honest and low-pressure, and stop when asked. Many investors prefer a respectful letter first.
See Maricopa County leads for 7 days, free
Real court filings with the owner and property matched. No credit card.