Investing in Ada County, Idaho: where motivated sellers show up in the court record
Ada County is a high-value, mostly owner-occupied market with little vacancy. Motivated sellers here are rarely sitting in empty houses. They show up in probate and foreclosure filings.
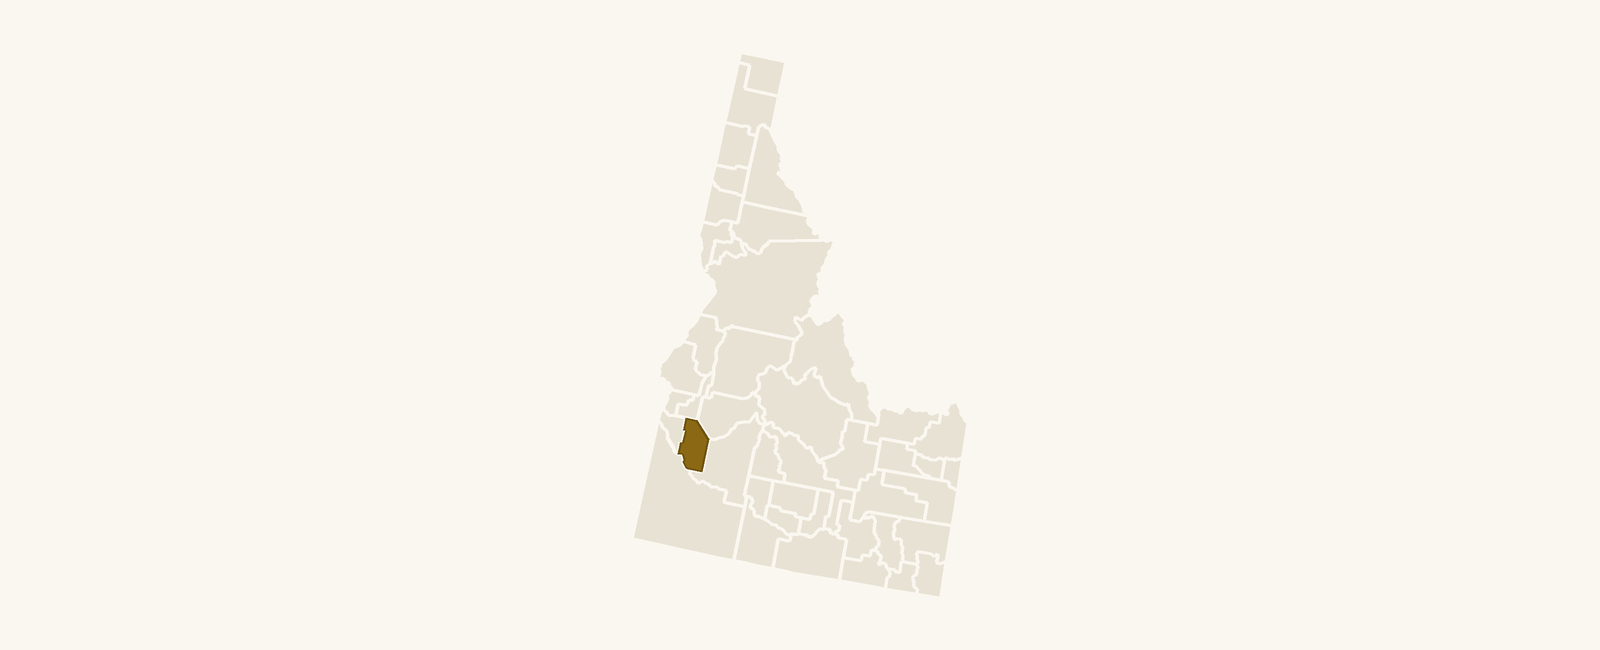
What Ada County's housing looks like for an investor
About 71% of homes in Ada County are owner-occupied, which makes this a market of households, not a market of landlords. If you are researching Ada County Idaho real estate investing, start there. The county has 205,068 housing units and 508,052 residents, and the county seat is Boise.
Single-family is the default product. About 74% of homes are single-family detached, compared with 61% across the U.S. That suits flippers, buy-and-hold investors and wholesalers who need a broad pool of end buyers, since most buyers here are shopping for a detached house.
Low vacancy means little slack. Just 4% of housing units are vacant, against 10% nationally. You will not find many obviously abandoned houses, so the sellers who are ready to deal tend to be occupied households or heirs.
The housing stock is also young. Only 4% of homes were built before 1940, compared with 12% nationally. That generally means fewer century-old plumbing and wiring surprises than in older eastern markets, though you should still inspect every property on its own merits.
On the demand side, 5,221 new housing units were permitted in 2025, up 2% from 2024. New construction is still arriving, which gives resale buyers alternatives and is worth weighing when you set your exit price.
Source: U.S. Census ACS 2023
Equity, rents and what the numbers mean for your deal
With a median home value of $476K, even a modest discount on an Ada County house is a large dollar amount. Mistakes in repair estimates or resale price cost real money, so build your numbers conservatively.
Equity is a bit thinner than the national picture. About 32% of owner-occupied homes have no mortgage, against 39% nationally. More owners here carry a loan, so in a probate or foreclosure situation you need to understand the payoff before you assume there is room for a deal.
For buy-and-hold math, HUD's Fair Market Rent for the Boise City area is $1,540 a month for a two-bedroom and $2,132 for a three-bedroom. Set those against a purchase price near the county's median value and the yield is tight. That pushes many investors toward discounted purchases, where the entry price is what makes the rental work.
- Price your repairs and holding costs before you talk to the seller, not after.
- Treat HUD rents as a benchmark, not a promise. Your actual rent depends on the specific house.
- Check the resale case against new construction your buyer could choose instead.
Which court filings come before a sale in Ada County, and why
A court filing is a signal that a household's situation has changed. It does not mean the owner wants to sell. Two filing types matter most here.
Pre-foreclosure. When an owner falls behind on a mortgage, the lender begins the foreclosure process. In Idaho that usually starts with a recorded notice rather than a lawsuit. The owner may be trying to refinance, catch up, or sell before the sale date. Some will welcome a clear, fair offer, and others will want nothing to do with it.
Probate. When a homeowner dies, the house often passes through a court-supervised estate. The person handling it may live out of state, may not want the house, and may be sharing the decision with siblings. With 16% of residents aged 65 or older (17% nationally), the share is close to the national picture, so probate is a steady source of conversations here, not an overwhelming one.
Divorce is a third situation that sometimes ends in a home sale. In Ada County, Family Court Services operates within the Magistrate Court at the Ada County Courthouse in Boise, offering parenting plan development and custody mediation. Those are people in the middle of a hard process, so any approach should be especially gentle.
The records behind these situations are public. Keystone's Ada County lead page covers pre-foreclosure and probate, delivered with the owner and property already matched.
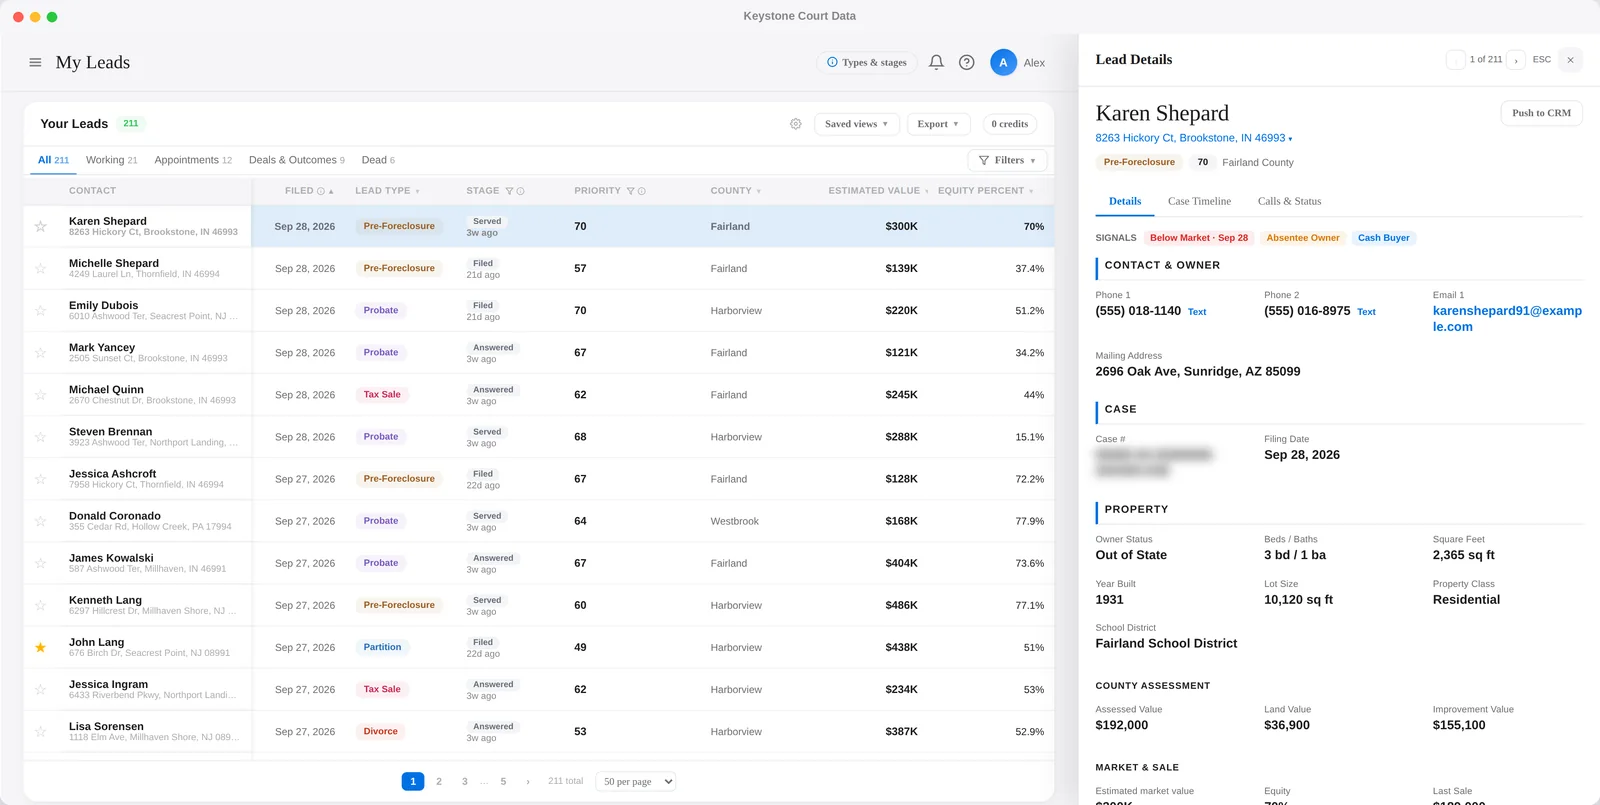
How foreclosure and probate work in Idaho, in plain terms
Idaho lenders commonly use a deed of trust, which allows a trustee to sell the property without a lawsuit. The rules for that process are in Idaho Code Title 45, Chapter 15. In practice, the owner gets a formal notice, a waiting period runs, and a sale date is set if the loan is not resolved. The exact timing and any right to cure depend on the documents and the statute, so confirm every deadline with an Idaho attorney before you rely on it.
Because this process does not run through a judge the way a lawsuit does, the owner may have fewer public court events to react to. That makes the notice itself an important moment. An owner who has just received it is often stressed and overwhelmed.
Probate runs through the court. Idaho handles estates under the Uniform Probate Code in Idaho Code Title 15, and the work happens in the county's court system. The court appoints a personal representative, who is generally the person with authority to sell estate property, sometimes subject to court steps or conditions. Who has authority, and what approvals are needed, varies by estate, so ask for documentation and have a title company or attorney verify it.
An estate can move slowly. Heirs may disagree, and there may be debts to settle before a sale closes. Plan your timeline and your financing around that.
How to approach owners respectfully and legally
The people in these filings are dealing with a death, a missed payment run or a family breakup. You are not entitled to their attention, so earn it.
Lead with help, not pressure. Introduce yourself plainly, say why you are contacting them, and make it easy to say no. A short, honest letter often works better than a call because it lets the person respond when they are ready.
Follow the calling rules. If you phone, scrub against the National Do Not Call Registry and follow Idaho's telemarketing rules as well as federal ones. Respect any request to stop contact the first time you hear it, and keep your own record of that request. Texting and automated dialing carry additional rules, so ask an attorney if you are unsure.
- Never imply you are affiliated with the court, the lender or the county.
- Do not suggest a deal is the only way out. Encourage owners to talk with a housing counselor, attorney or the personal representative's own advisers.
- Be clear that you are an investor, and put your terms in writing.
- With a probate property, speak with the personal representative, not with grieving relatives who have no authority to sell.
What to look for before you make an offer
Distress creates urgency for the seller, but it should never rush your own diligence. In a market with a median home value of $476K, a missed problem is expensive.
- The payoff and liens. Have a title company confirm what is owed before you commit to a price. An owner with a loan balance may have much less room than the home value suggests.
- Who can sign. In an estate, confirm in writing who holds authority. In a foreclosure, confirm the current status and timeline with an attorney.
- Condition. The housing stock is mostly newer, but a home may have been neglected during a hard stretch. Inspect it before you assume cosmetic work only.
- Your exit. Compare your resale or rental numbers with HUD's $1,540 (two-bedroom) and $2,132 (three-bedroom) rents, and remember new construction is still being permitted.
- Occupancy. With only 4% of units vacant, the house is likely lived in. Plan for a respectful, realistic move-out timeline.
If you want to see the filings that fit these situations in Ada County, here is how Keystone delivers them. Whatever source you use, the deal still depends on your diligence and your conduct with the owner.
Questions investors ask
Is Ada County a good place to invest in real estate?
It offers a deep pool of single-family homes, low vacancy and a high median home value of $476K. That means large potential equity but also large downside if you misjudge repairs or resale. Buy-and-hold yields are tight against HUD rents, so many investors focus on discounted purchases.
Does Idaho foreclose through the courts?
Most Idaho foreclosures on deeds of trust are handled by a trustee outside court, under Idaho Code Title 45, Chapter 15. Timing and the owner's options depend on the loan documents and the statute. Confirm any deadline with an Idaho attorney.
Who can sell a house in probate in Ada County?
Generally the court-appointed personal representative, sometimes with court approval depending on the estate. Ask for written proof of authority and have a title company or attorney verify it before you sign anything.
Can I call homeowners in foreclosure or probate?
You can, but you must follow the National Do Not Call Registry and Idaho's telemarketing rules, and you must stop when asked. Many investors prefer a short letter, which is less intrusive for someone in a hard situation. Ask an attorney if you are unsure what applies to you.
Where do I get Ada County pre-foreclosure and probate leads?
The underlying filings are public. Keystone delivers Ada County pre-foreclosure and probate filings with the owner and property already matched, and you can try a county free for 7 days with no credit card.
See Ada County leads for 7 days, free
Real court filings with the owner and property matched. No credit card.