Aitkin County covers more than 1,800 square miles of north-central Minnesota, but its population sits at just around 16,000 people. That ratio matters for investors. A small, income-volatile workforce spread across a largely rural county creates persistent financial stress among property owners, and that stress shows up regularly in Aitkin County District Court filings. If you're looking for pre foreclosure leads Aitkin County MN, the window to reach a motivated seller before anyone else does is real, but it's narrow.
Key Takeaways
- Aitkin County's seasonal economy creates recurring pre-foreclosure activity, especially among year-round residents in Aitkin City and McGregor.
- Properties here typically range from $130,000 to $210,000, with lakefront and cabin properties commanding significant premiums. Pre-foreclosure deals often close 20 to 35% below comparable market values.
- Keystone Court Data delivers pre-foreclosure filings the same day they hit the public record, before any aggregator or list service picks them up.
- Every lead includes full property data, owner contact information, motivation scoring, and an absentee owner flag.
The core problem with most lead sources is that by the time a name appears on a purchased list, a dozen other investors have already dialed that number. Pre-foreclosure is the one lead type where timing genuinely determines whether you get a conversation or a voicemail. Court filings are public record the moment they're entered. The investor who reaches a homeowner in the first day or two after filing faces a very different conversation than the one showing up three weeks later.
This piece covers what pre-foreclosure leads look like in this specific market, what data comes with each filing, why same-day delivery changes your conversion math, and how Keystone Court Data pulls it all together for Aitkin County subscribers.
What Makes Aitkin County a Viable Pre-Foreclosure Market
Aitkin County's economy leans heavily on seasonal tourism, timber, and agriculture. That means a large portion of working residents deal with income that fluctuates by month, often significantly. When a slow tourism season or a bad timber contract collides with a fixed mortgage payment, the gap shows up in court filings.
The residential market here is bifurcated. You have year-round working-class homeowners in Aitkin City and McGregor, where median values tend to fall in the $130,000 to $180,000 range, and then you have seasonal and lakefront properties on lakes like Sandy Lake and Mille Lacs, where prices can climb well above that band. Pre-foreclosure activity clusters around the year-round residential pockets, where income volatility hits hardest and equity positions are thinner.
That clustering is useful. It means your outreach can be targeted. A homeowner in Aitkin City who's three months behind on a $145,000 mortgage is in a very different position than a cabin owner on a premium lake lot, and the deals you structure will reflect that difference.
What Data Comes with Every Pre-Foreclosure Lead in Aitkin County
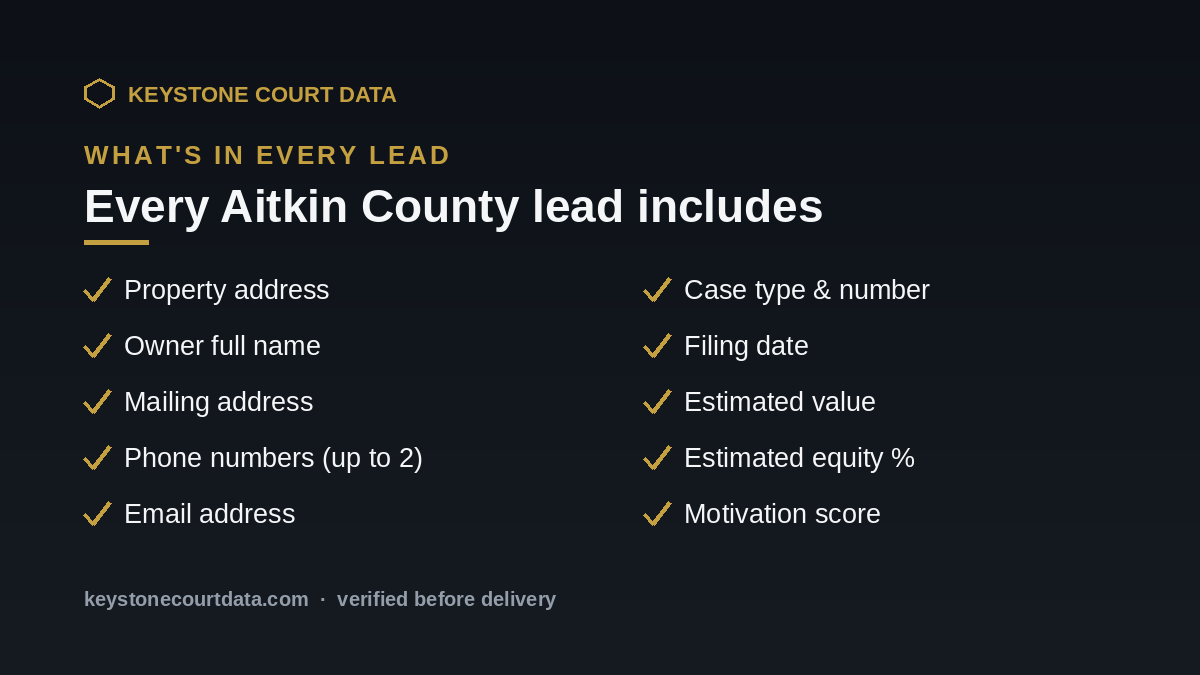
A raw court filing tells you someone is in trouble. It doesn't tell you much else on its own. Keystone pulls each Aitkin County pre-foreclosure filing and builds it into a usable lead record before delivering it to your account. Here's what's included with every record:
- Owner name and mailing address, including an absentee flag if the owner doesn't live at the property
- Property address and parcel information
- Estimated property value and equity position based on verified public data
- Lender name and loan information from the filing
- Filing date and case number for direct court record verification
- Motivation score, which weights factors like equity, days since filing, absentee status, and property condition signals
- CRM-ready formatting for direct import into your existing workflow
The absentee flag deserves a specific mention in a county like this one. Aitkin County has a meaningful inventory of properties owned by people who don't live there full-time. When a cabin or seasonal property owner falls behind on payments, they're often more motivated to sell quickly and cleanly than a primary resident who has nowhere else to go. That flag helps you prioritize your outreach accordingly.
How the Pre-Foreclosure Timeline Works in Minnesota
Minnesota is a non-judicial foreclosure state for most residential mortgages, which means lenders can proceed by advertisement without going through the court system. However, judicial foreclosure is still used in certain cases, and the pre-foreclosure window before any auction date gives investors meaningful time to work a deal.
The sequence from filing to foreclosure sale in Minnesota typically runs several months, sometimes longer depending on the case and the lender. That window is your working period. Here's how it tends to unfold:
- Filing date: The public record is created. This is when Keystone delivers the lead to your account.
- First 30 days: The highest-conversion window. The homeowner is aware of their situation but hasn't yet been contacted by most investors or attorneys.
- Days 31 to 90: Still viable, but competition increases and the homeowner may have already spoken with other parties.
- Beyond 90 days: Auction timelines become more concrete. Deals can still close, but negotiating leverage shifts.
The math is straightforward. Being first to call on day one is materially different from being the fourth call on day twenty-two. That's why same-day delivery from public court records, rather than weekly or monthly batch updates from a list aggregator, actually changes outcomes.
In a rural market like Aitkin County, the investor who calls on day one isn't just early. They're often the only one who called that week.
Why Court-Direct, Same-Day Delivery Matters Here
Most lead services aggregate data on a delay. They pull from secondary sources, batch-process records, and deliver lists days or weeks after a filing hits the public docket. In a high-volume urban market, you might still find motivated sellers in that window. In a rural county where the filing volume is lower and the homeowner is less likely to have been bombarded with investor calls, the gap between first contact and everyone else is much wider.
Keystone monitors Aitkin County public court records every day. When a new pre-foreclosure case is filed, it's processed and delivered to your account the same day. No batch delays, no waiting for a weekly export. The lead is in your CRM while the homeowner is still figuring out their next move.
This is a non-exclusive subscription, meaning other investors can also subscribe to Aitkin County leads. The edge isn't a subscriber limit. It's being the one who actually calls first. That requires same-day data, not last week's list.
You can review current subscription tiers and pricing at keystonecourtdata.com/pricing. Subscriptions come in three tiers, priced by market size, with a 12-month price lock at signup so your costs don't shift mid-year.
What Deals Actually Look Like in This Market
Investors working Aitkin County pre-foreclosures typically find properties where the owner's primary goal is avoiding the public stigma and credit damage of a completed foreclosure, not maximizing their sale price. That motivation is what creates the discount. Properties here have historically traded at 20 to 35% below comparable market values when acquired through pre-foreclosure negotiation.
On a $160,000 year-round residential property in Aitkin City, that range translates to a potential acquisition price between roughly $104,000 and $128,000. On a higher-value lakefront property, the nominal discount is larger even if the percentage is similar. The specific numbers depend on the individual deal, the equity position, and how far the foreclosure process has progressed.
The key inputs you need to evaluate any deal quickly are the ones Keystone includes in every lead record: estimated value, equity position, lender information, and days since filing. With those in hand, your first call can be a real conversation rather than a fishing expedition.
For a full view of active Aitkin County filings and to see the types of cases currently in the system, visit the Aitkin County real estate leads page on the Keystone platform.
How to Use the Platform Effectively for Aitkin County
The motivation score on each lead is worth using as your first filter, not your only one. A high score reflects a combination of factors: thin equity, longer time since filing, absentee ownership, and other signals that suggest a seller who needs to move. But context matters. A lower-scored lead on a lakefront property with significant equity might still be worth a call if your strategy includes higher-value acquisitions.
The absentee flag is your second filter in this market specifically. Aitkin County has a real inventory of properties where the owner lives elsewhere, and those owners often have less emotional attachment to the property and more urgency to resolve the situation cleanly. Sort by absentee flag, sort by motivation score, and prioritize your first calls from there.
CRM integration means you're not manually entering lead data. Every filing comes in formatted for direct import, so your follow-up sequences can start the same day the lead arrives.
Frequently Asked Questions
How quickly do I receive pre foreclosure leads for Aitkin County after a case is filed?
Keystone monitors Aitkin County public court records daily. When a new pre-foreclosure case is filed and enters the public record, it's processed and delivered to your account the same day. You're not waiting for a weekly batch or a third-party aggregator to pick it up.
Is the Aitkin County subscription exclusive to one investor?
No. Aitkin County is a non-exclusive market, meaning multiple subscribers can access the same leads. The platform doesn't cap subscriber counts. The advantage comes from being the first to call, which requires same-day data. If you're working from a list that's several weeks old, exclusivity wouldn't help you anyway.
What types of properties show up most often in Aitkin County pre-foreclosure filings?
Pre-foreclosure activity in Aitkin County tends to concentrate in year-round residential properties in and around Aitkin City and McGregor, where working-class homeowners face the most income volatility. Seasonal and recreational properties do appear, and the absentee flag in each lead record helps you identify those quickly.
What if I want to target only properties above a certain value, like lakefront cabins?
Each lead includes estimated property value and equity data, so you can filter your pipeline by value range. The platform's motivation scoring and property data fields give you enough information to prioritize before you make your first call, whether you're targeting entry-level residential or higher-value lakefront inventory.
How do I know if a pre-foreclosure deal in Aitkin County is worth pursuing?
Start with the equity position and the days since filing. A homeowner with thin equity who filed 45 days ago is under more pressure than one with substantial equity who filed last week. Combine that with the motivation score, the absentee flag, and the property value estimate, and you have a working picture before you ever dial. The goal is to prioritize your calls, not to pursue every filing equally.
Aitkin County won't generate the filing volume of a metro market. What it offers is a smaller field of competition, motivated sellers who haven't been contacted by a dozen other investors, and properties that can trade at meaningful discounts when you reach them early.
Work Aitkin County before the competition does
See real Aitkin County court filings from the last few days. 7-day free trial, no credit card.
Claim Aitkin County → See pricing